Cyber Insurance - Recover Faster from Ransomware and Data Breaches
Cyber Insurance Get Quote
Click to submit your details and receive a customised quote. Have questions about your coverage? Our team will call you within 1 business day.
Our Insurance Partners
Know your policy
Everything you need to know
What is Cyber Insurance
Financial Protection When a Cyber Incident Strikes
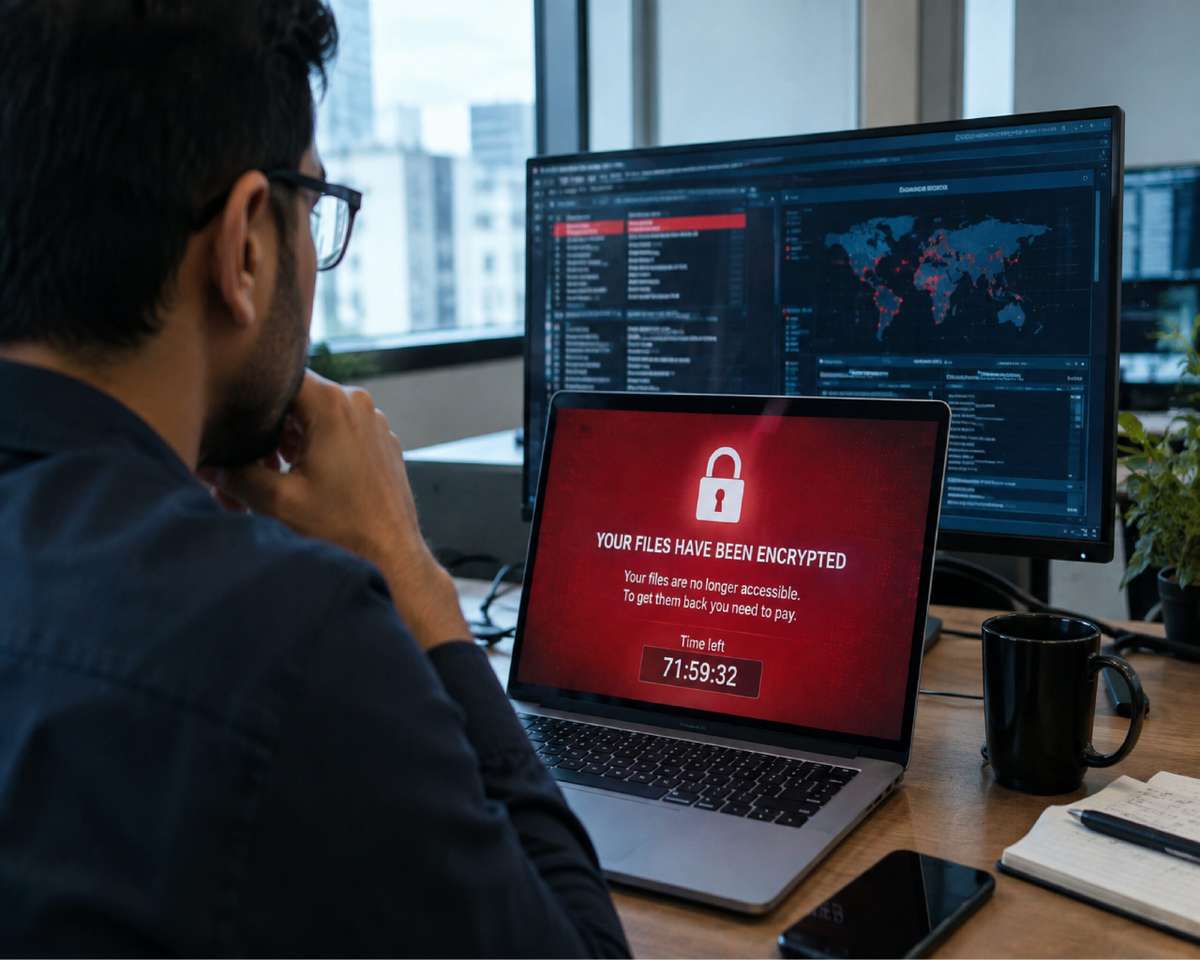
Cyber insurance covers financial losses and response costs arising from cyber incidents – data breaches, ransomware, business interruption from system outages, and liabilities to third parties for leaked personal data. It bundles incident response, forensics, legal fees, notification costs, regulatory defence and sometimes ransom payments (subject to local laws and insurer terms).
Why Is This Policy Vital?
Because cyberattacks no longer announce themselves
Ransomware and business-interrupting attacks can stop operations in hours — cyber cover accelerates response and recovery.
Indian law now sets tight deadlines: cyber incidents must be reported to CERT-In within 6 hours, and personal data breaches to the Data Protection Board within 72 hours under the DPDP Rules, 2025. Penalties under the DPDP Act go up to ₹250 crore. Cyber cover pays for the legal, forensic and notification work this requires.
For fintechs and data-heavy startups, a single breach can erode customer trust; cover buys time and expert support.
Know your policy
Understand your insurance before buying
Who Needs Cyber Insurance?
Fintechs & Banks
Payments and data exposures.
Healthcare & Labs
Patient data & privacy risks.
E-commerce & D2C
Customer PII and payment flows.
Manufacturing (Industry 4.0)
OT/ICS threats and production downtime.
SMEs & Professional Services
Ransomware and client-data liability.
Schools & EdTech
Student data and online learning platforms.
Types / Add-ons Commonly Offered
Data Breach Response & Notification Costs
Compliance and communication support.
Cyber Extortion / Ransom Payment & Negotiation Costs
Negotiation support coverage.
Business Interruption
Dependent & non-dependent coverage.
Forensic Investigation & Malware Removal
Technical response coverage.
Regulatory Defence & Fines
Where insurable.
Contingent Network Interruption
Vendor/cloud outages.
What Cyber Insurance Pays For
Incident Response & Forensics
Hires & investigations to contain breaches.
Ransomware & Extortion Costs
Negotiation and (where allowed) ransom payments.Negotiation costs and, where the policy and law permit, extortion payments.
Data Restoration & IT Recovery
Get systems back online.
Business Interruption
Lost profit while systems are down.
Legal & Regulatory Costs
Notification, defence and penalties where covered.
PR / Reputation Management
Crisis comms support.
Third-party Liability
Suits from customers/partners over leaked data.
Fraud & Funds Transfer Loss
Cyber-enabled fraud cover where specified.
Inclusions & Exclusions
✓Inclusions
- First-party incident response costs (forensics, legal, notification).
- Cyber extortion response and negotiation costs (subject to local / insurer rules).
- Business interruption due to cyber events and dependent vendor outages (if included).
- Third-party liability for privacy breach claims (defence and indemnity).
✗Exclusions
- Known or unreported breaches prior to policy inception (pre-existing incidents).
- Criminal, fraudulent acts by insured’s executives (intentional illegal acts).
- Bodily injury / physical damage exclusions unless explicit (some cyber-physical endorsements exist).
- War, state-sponsored acts and sanctioned transactions (often excluded).
FAQs
Some policies cover ransom payments and negotiation costs, but coverage depends on policy wording and local law; many insurers require strict incident response steps.
Regulatory fines are sensitive and may be excluded; some policies offer limited coverage or defence-only assistance - check your wording.
Yes - SMEs are frequent ransomware targets and often lack the internal resources to handle incidents fast. Cyber insurance helps bridge that gap.
Incident timelines, logs, forensic reports, vendor contracts and evidence of security controls (backup, MFA) help the insurer process claims.
Contingent business interruption for cloud/vendor outages can be included as an add-on - declare critical suppliers to ensure cover.
Premiums depend on industry, revenue, security posture (controls), incident history, and policy limits/deductibles.