
Protect Workers, Protect Your Business!
Our Insurance Partners
Industry Get Quote
Click to submit your details and receive a customised quote. Have questions about your coverage? We'll get back to you soon.
Know your policy
Everything you need to know
What is Workmen Compensation Insurance
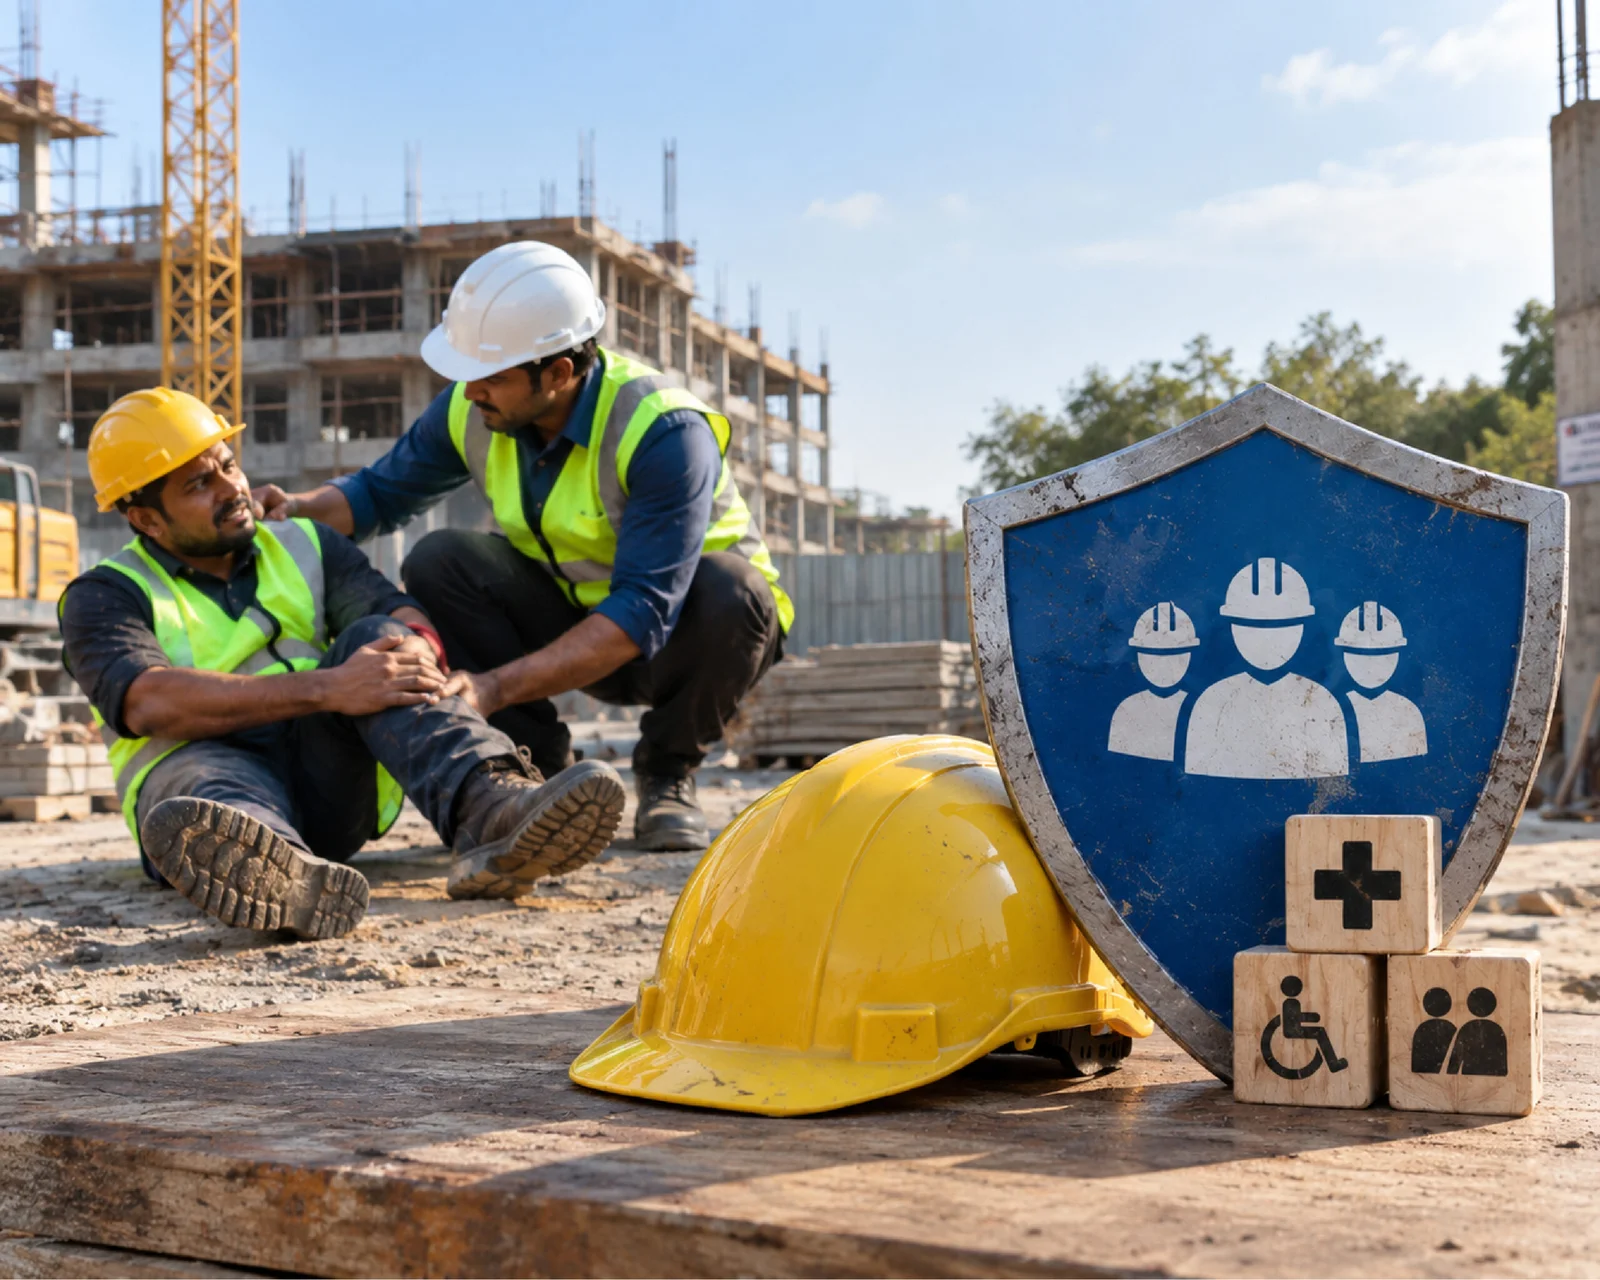
Workmen Compensation: Your Legal Liability’s Safety Net!
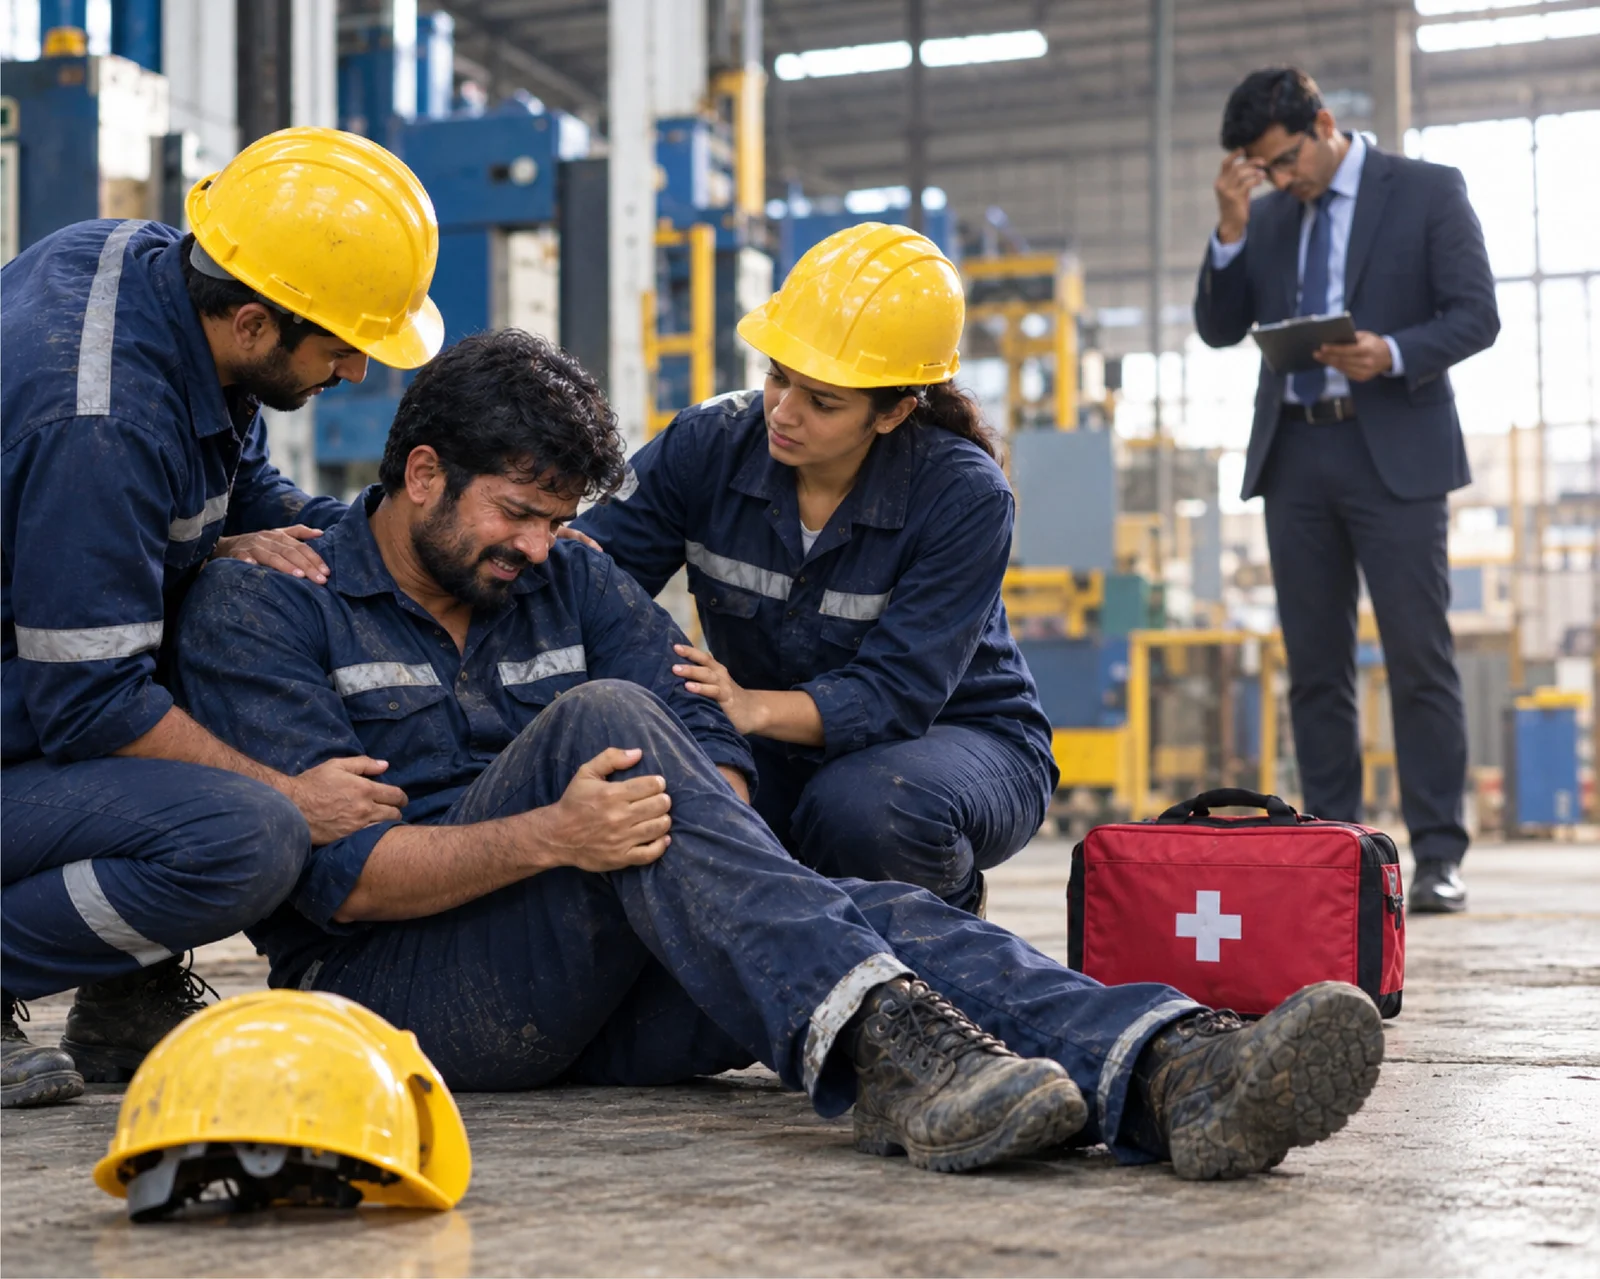
Think of workmen compensation insurance as having a legal shield that automatically activates whenever workplace accidents happen! It’s comprehensive protection covering employer’s statutory liability under the Employees’ Compensation Act, 1923 for employee injuries, disabilities, or deaths arising from workplace accidents.
Whether you’re running construction sites, factories, or logistics operations, WC insurance ensures that when unfortunate accidents occur, your workers get compensated and your business doesn’t get bankrupted. It’s like having an emergency fund specifically for workplace mishaps—legally compliant and financially essential!
Why Is This Policy Vital for Employers
Because One Workplace Accident Can Cost More Than Annual Profits!
Under the Employees’ Compensation Act 1923, employers are legally liable to compensate injured workers—death compensation is ₹1.2 lakh minimum (50% of monthly wages × relevant factor, whichever is higher); permanent total disability is ₹1.4 lakh minimum (60% of wages × factor). A single factory accident involving 5 workers can trigger ₹20-30 lakh liability! WC insurance is the difference between “unfortunate incident” and “business closure notice.” It’s survival insurance for employers!
Know your policy
Understand your insurance before buying
What Workmen Compensation Insurance Covers
Accidental Death
Compensation payable to dependents in case of fatal workplace accident.
Permanent Total Disability
Compensation for complete and permanent inability to work.
Permanent Partial Disability
Proportionate compensation based on disability percentage.
Temporary Disability
Compensation during temporary inability to work due to injury.
Medical Expenses
Hospitalization and treatment costs for workplace injuries.
Occupational Diseases
Coverage for illnesses arising from work conditions.
Transportation Costs
Costs of transporting injured worker for medical treatment.
Legal Defense Costs
Expenses for defending compensation claims in court.
Contractual Liability
Coverage extended to contractors and subcontractors.
Funeral Expenses
Reimbursement of funeral costs in case of workplace death.
Dependent Compensation
Financial support payable to dependents of the worker.
Rehabilitation Costs
Costs for medical rehabilitation after workplace injury.
Who Needs Workmen Compensation Insurance?
Manufacturing & Factories
Industrial operations with machinery, assembly lines, and production processes face high workplace accident risks requiring mandatory WC coverage.
Construction & Contractors
Building sites, infrastructure projects, and construction activities involve hazardous work requiring comprehensive worker injury protection.
Logistics & Warehousing
Material handling, loading-unloading operations, and warehouse work create injury risks needing statutory compensation coverage.
Mining & Extraction
Underground mining, quarrying, and mineral extraction operations face extreme workplace hazards requiring enhanced WC protection.
Plantations & Agriculture
Commercial farming, tea estates, and agricultural operations with manual workers need WC coverage under the Act.
Security & Facility Services
Security guards, housekeeping staff, and facility management workers require employers' liability coverage for workplace injuries.
Types / Add-ons Commonly Offered
Basic WC Policy
Statutory compensation under Employees' Compensation Act.
WC with Medical Extension
Additional medical expense coverage (up to ₹25,000-₹1 lakh).
WC with Occupational Disease Cover
Coverage for work-related illnesses and diseases.
Contractual Liability Extension
Coverage for contractors and subcontractors.
Foreign Workers Cover
Extended coverage for Indian workers employed abroad.
Common Law Liability
Enhanced cover beyond statutory limits.
Inclusions & Exclusions
✓Inclusions
- Death Compensation — 50% of monthly wages × relevant factor OR ₹1.2 lakh (whichever is higher) payable to dependents.
- Permanent Total Disability — 60% of monthly wages × relevant factor OR ₹1.4 lakh (whichever is higher) for complete inability to work.
- Permanent Partial Disability — Proportionate compensation based on disability percentage as per Schedule I of the Act.
- Medical Expenses — Actual hospitalization and treatment costs (if medical extension cover is opted).
- Legal Defense Costs — Expenses for defending compensation claims in labor courts and tribunals.
✗Exclusions
- Willful Disobedience — Injuries from deliberately ignoring safety rules and regulations excluded.
- Intoxication — Accidents occurring when worker is under influence of alcohol or drugs excluded.
- Outside Employment Scope — Injuries occurring outside workplace or working hours typically excluded.
- War & Civil Unrest — Injuries during war, riots, and civil commotion usually excluded.
- Pre-existing Conditions — Disabilities and diseases existing before employment not covered under standard policies.
Faq's
Yes! Mandatory for employers in Schedule II industries (factories, construction, mining, etc.) under Employees' Compensation Act 1923!
Yes! Both permanent and contractual workers must be covered. Principal employer remains liable—better to insure!
ESI applies to establishments with 10+ employees earning up to ₹21,000/month; WC covers ALL workers in specified industries!
Based on total wages, industry risk category, and number of workers. High-risk industries = higher premiums!
With occupational disease add-on, yes! Standard policies may exclude; check policy wording for inclusions!
No! Worker claims from employer; employer gets reimbursed by insurance. Employer remains legally responsible!