
Accidents Happen. Legal Bills Don’t Have To.
CGL Insurance Get Quote
Click to submit your details and receive a customised quote. Have questions about your coverage? Our team will call you within 1 business day.
Our Insurance Partners
Know your policy
Everything you need to know
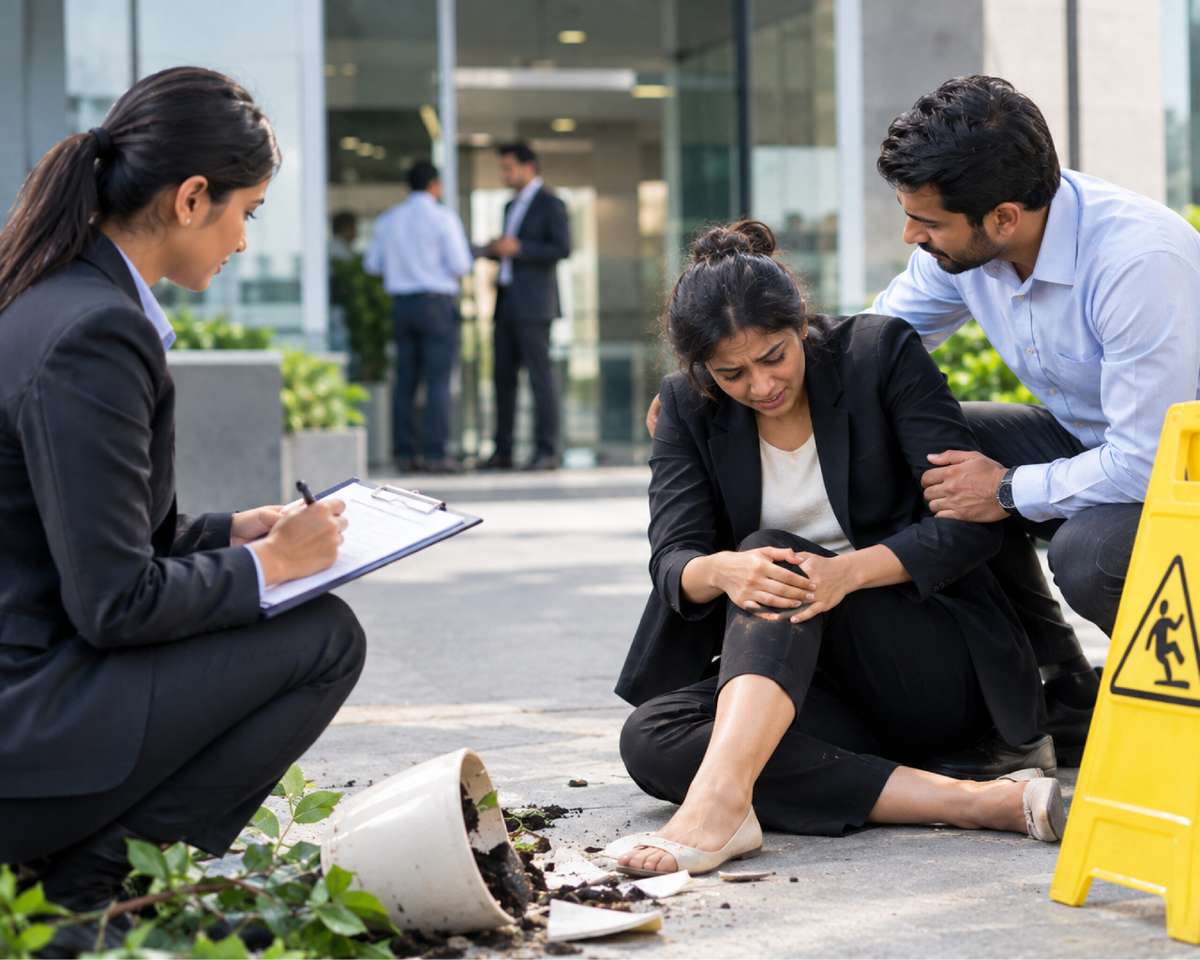
What is CGL Insurance?
When Someone Gets Hurt, We Step In
Commercial General Liability covers third-party claims for bodily injury or property damage arising from your business operations or premises. It typically also covers personal and advertising injury (libel, slander), and legal defence costs – protecting cashflow from lawsuits and settlements.
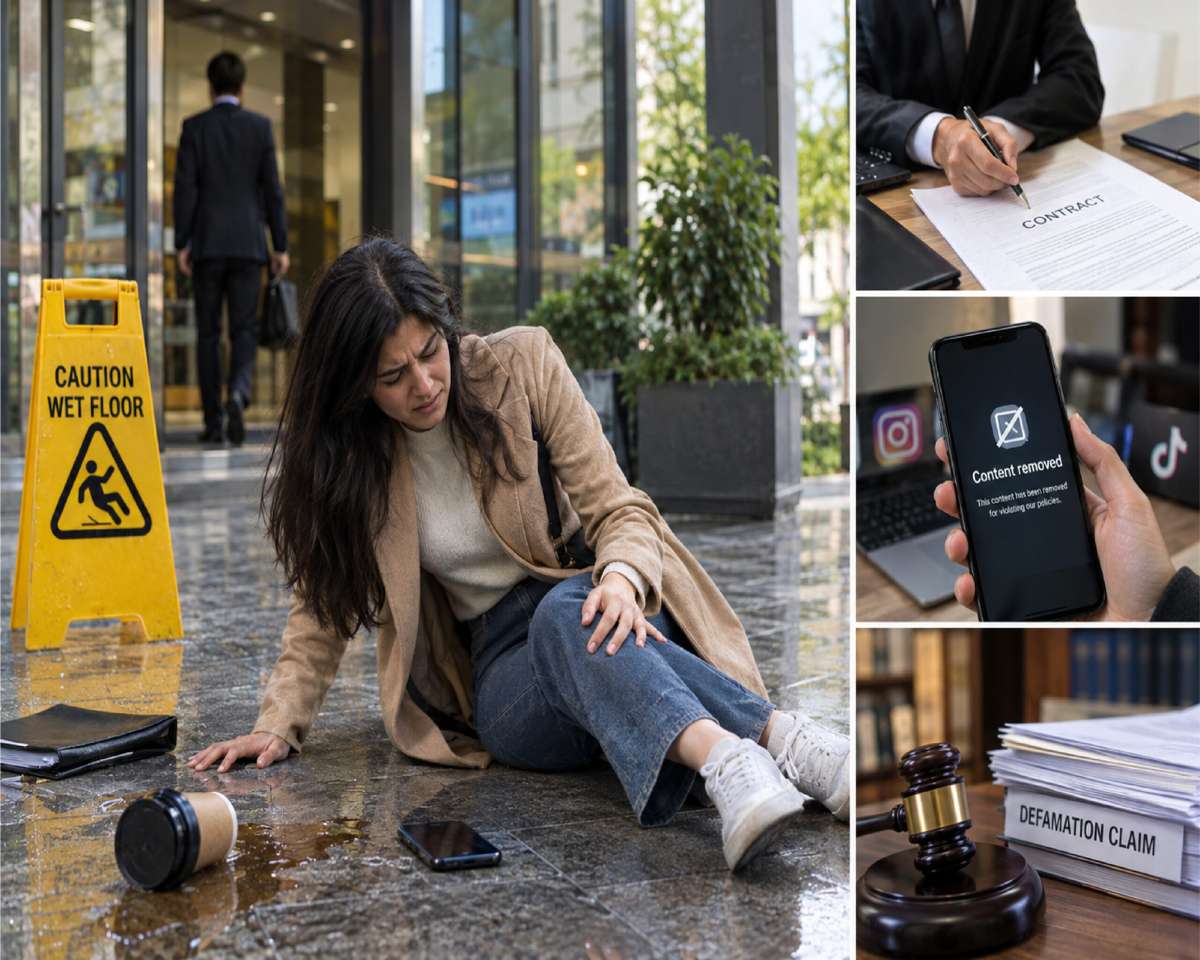
Why Is This Policy Vital?
One serious accident can lead to large compensation and legal bills.
Premises risk is real – slips, trips or falling signage can lead to medical and legal bills.
Vendor & contract clauses often demand CGL as a prerequisite for work or events.
Claims over advertising (defamation, copyright or trademark infringement in your ads) are increasing – CGL's advertising injury section can respond.
Know your policy
Understand your insurance before buying
Who Needs CGL?
Retail Chains & Shops
Customer injuries & in-store damage.
Events & Exhibitions
Audience injury and stall damage exposure.
Contractors & Site Managers
Third-party property damage during work.
Restaurants & Hotels
Foodborne illness claims, slip & fall.
SaaS / Offices with physical premises
Customer visits and premises liabilities.
Types / Add-ons Commonly Offered
Premises & Operations Liability
Covers injury or damage tied to your site or daily operations.
Products & Completed Operations Liability
Covers claims arising after your product or work is delivered.
Personal & Advertising Injury (libel / slander)
Reputational and marketing-related claims.
Legal Defence Costs / Indemnity Extension
Legal representation costs, even for unfounded claims.
Tenant's Liability (for rented premises)
Covers your liability for fire or other damage to premises you rent.
Cross-liability (multiple insured parties)
Covers claims between multiple insured parties.
What CGL Pays For
Third-party Bodily Injury
Medical and legal costs.
Third-party Property Damage
Repair or replacement costs.
Legal Defence & Settlement Costs
Representation up to policy limit.
Advertising Injury
Libel, slander and copyright infringement in your advertising.
Products Liability
If included in your policy.
Tenant's Liability
Damage to rented premises.
Medical Expenses
Medical expenses of injured third parties, regardless of fault, up to a small sub-limit.
Cross-liability settlements
Between multiple insured parties.
Inclusions & Exclusions
✓Inclusions
- Third-party bodily injury & property damage arising from operations/premises.
- Legal defence costs up to policy limit.
- Personal & advertising injury claims (per policy wording).
- Products & completed operations (depending on wording).
✗Exclusions
- Intentional or criminal acts by insured.
- Contractual liabilities assumed beyond policy unless endorsed.
- Employee injury (covered under an Employees' Compensation policy, as required by the Code on Social Security, 2020).
- Pollution (other than sudden and accidental, if endorsed).
- Professional advice (needs E&O).
- Damage to your own property or goods in your care.
- Product recall costs.
FAQs
No - employee injuries are typically covered under workers' compensation or employer's liability, not CGL.
Yes - online defamation, copyright takedown requests or false advertising claims can trigger advertising injury coverage.
Products liability may be included under CGL if the product/completed operations extension is present; otherwise, separate product liability insurance is recommended.
Limits are based on exposure, contract requirements and industry norms - brokers usually recommend limits tied to contract caps and estimated claim size.
Some policies offer worldwide coverage or defence costs worldwide - check territorial limits and exclusions.
Yes - some CGLs allow sudden/accidental pollution endorsements, but long-term contamination usually needs specialised cover.