
Stolen? Not on Our Watch - Burglary & Theft Cover for Business
Burglary and Theft Insurance Get Quote
Click to submit your details and receive a customised quote. Have questions about your coverage? Our team will call you within 1 business day.
Our Insurance Partners
Know your policy
Everything you need to know
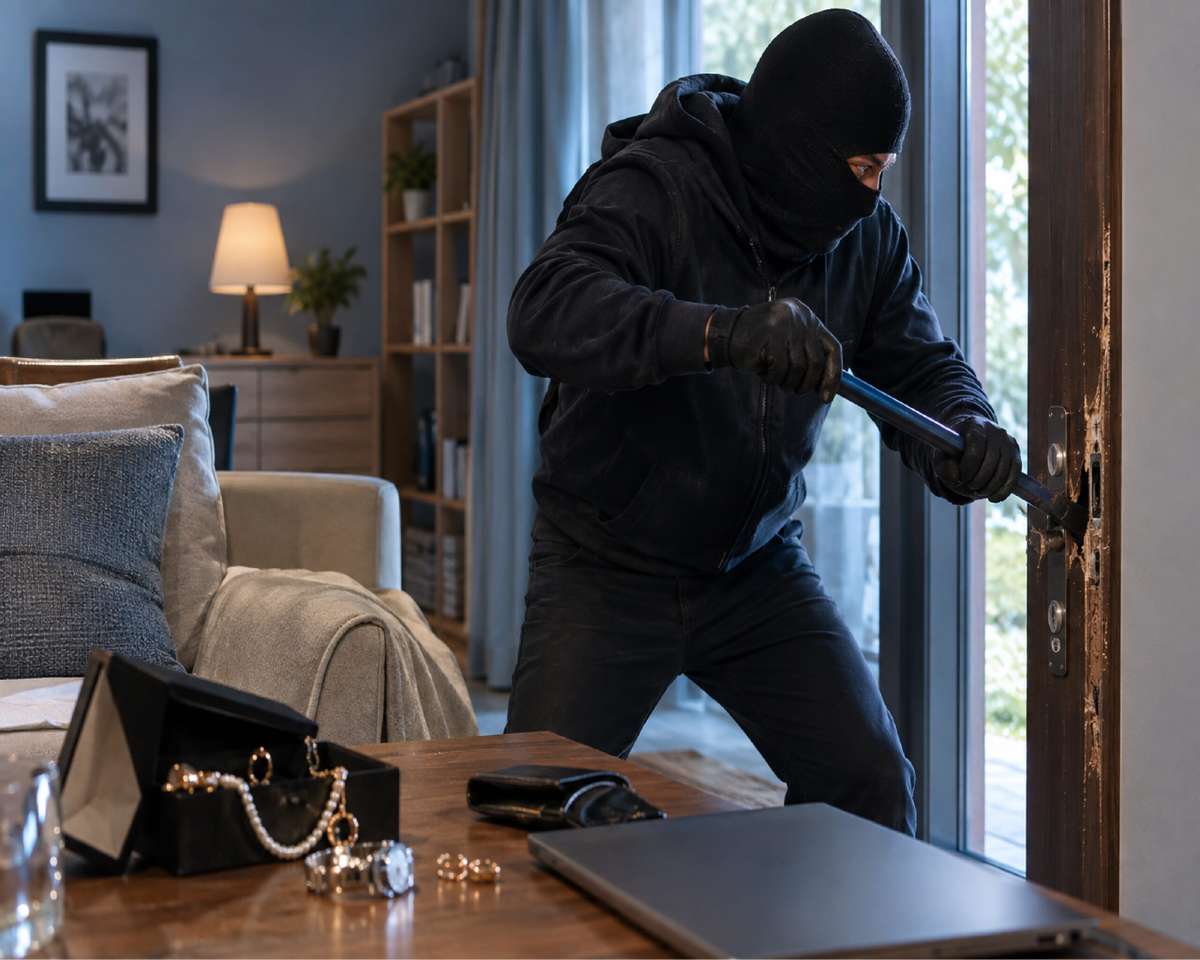
What is Burglary & Theft Insurance
When Someone Breaks In, We Break Out the Cover
Burglary & Theft Insurance pays for loss or damage to insured property resulting from forcible and violent entry (burglary), robbery, or attempted theft. It also typically covers damage to the premises caused during the crime (broken locks, forced doors). Policies vary – some cover mysterious disappearance only if specific conditions are met. Prompt police FIR and documentation are essential for a smooth claim.
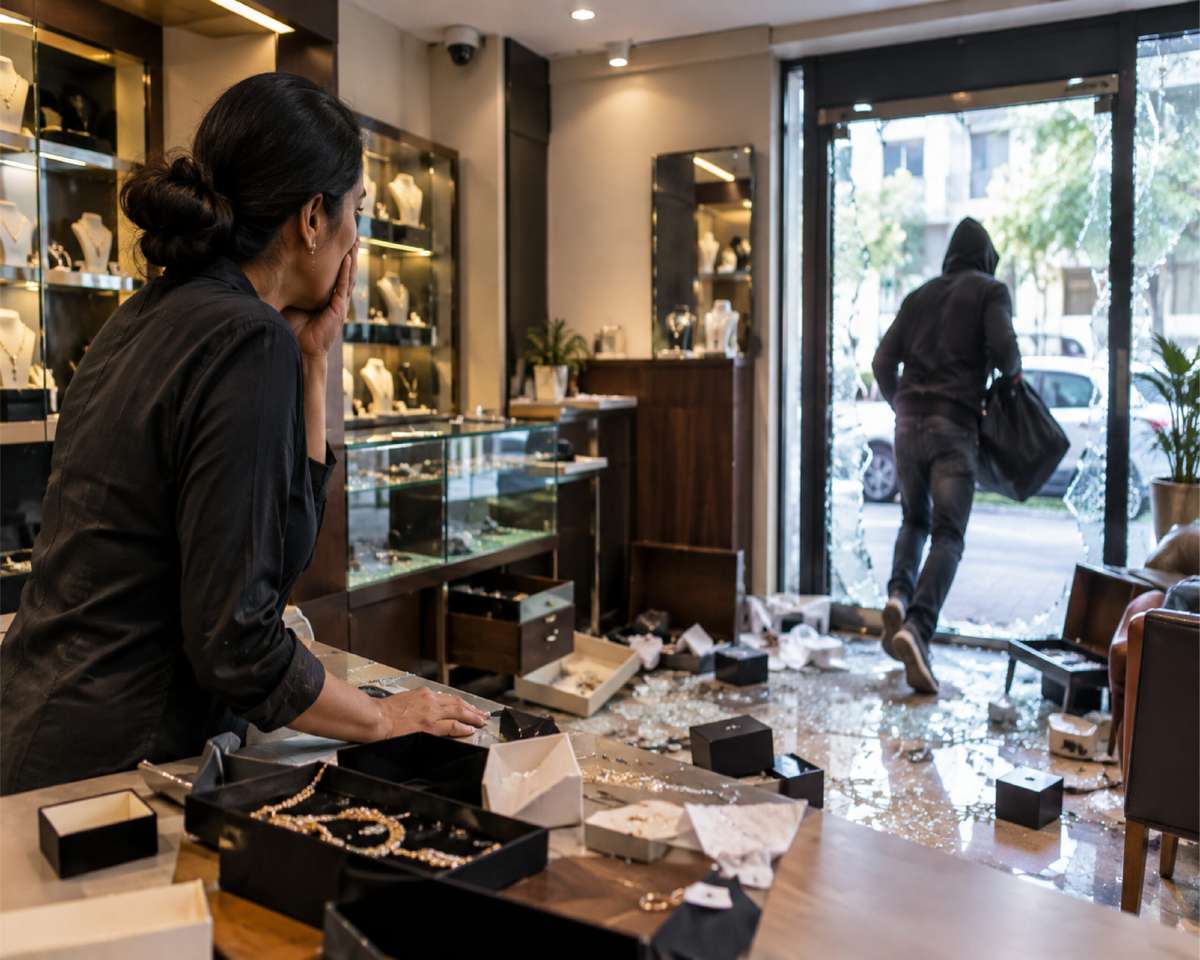
Why Is This Policy Vital?
Because stock & trust vanish faster than cash
A single smash-and-grab can wipe out a week or month of sales for small shops – burglary cover helps recover the value of stolen stock, subject to policy terms.
Warehouses with bulk inventory are high-risk zones – policy options provide first-loss or scheduled basis cover to manage exposure.
For retail chains and jewellers, timely claims protect customer trust and keep shelves stocked.
Know your policy
Understand your insurance before buying
Who Needs Burglary & Theft Insurance?
Retail Stores & Malls
Stock and POS protection.
Warehouses & ICDs
Bulk inventory and storage risks.
Offices & Commercial Premises
Equipment, servers and files.
Jewellery & High-Value Retail
Scheduled/high-value item protection. Jewellers should use a Jewellers Block policy, which covers stock on premises, in transit and with staff.
Small Traders / Home-Based Sellers
Flexible options for home-office inventories.
Types / Add-ons Commonly Offered
Burglary (Forcible Entry)
Main section for violent entry losses.
Theft & Robbery
Cover for snatching and armed acts.
First-Loss Basis
Cover a % of total stock for rotating inventories.
Money in safe and in transit
Usually a separate Money Insurance policy or a section of a package policy.
Mysterious Disappearance
Limited option with strict evidence conditions.
Damage to Premises
Forced entry repair (locks/doors/windows).
What Burglary & Theft Policy Pays For
Forceful Entry Losses
Stolen goods due to burglary.
Robbery & Hold-Up
Theft involving force or threat.
Damage to Premises
Repairs after break-in.
Contents & Inventory
Stock and fittings stolen/damaged.
Cash-in-Safe & Transit
Insured cash at premises or on transit.
First-Loss Stock Cover
Rotating inventory protection.
Exhibition / temporary storage
S Cover for stock moved to an exhibition or another location for a short period.
Inclusions & Exclusions
✓Inclusions
- Burglary & Housebreaking — Loss due to forcible/violent entry.
- Robbery / hold-up — Theft on the premises by force or threat of force (where the hold-up extension is taken).
- Breakage & Damage — Repair costs for forced entry damage.
- First-Loss Stock (if selected) — Percentage-based cover for inventory.
- Money-in-Safe & Transit — Daily takings and transit (if opted).
✗Exclusions
- Voluntary Parting / Fraudulent Parting — Losses due to deceit without forcible entry are often excluded.
- Unattended / Unsecured Property — Premises left unlocked for prolonged periods may void claim.
- Wear & Tear / Gradual Deterioration — Not covered.
- War, Terror & Nuclear Events — Standard political exclusions.
- Late reporting — Delay in informing the police or the insurer can lead to the claim being reduced or rejected. Report immediately.
FAQs
Burglary requires forcible and violent entry or exit. Theft without such signs is generally not covered under a standard burglary policy unless a theft extension is added.
Yes - timely police FIR is essential for burglary/theft claims in India and insurers typically require it as part of the claim process.
Yes - first-loss stock cover is available where a percentage of total stock is insured to reflect rotating inventories. Premiums depend on turnover and selected percentage.
Sometimes, as an optional extension with strict conditions and higher premium; many policies exclude it by default.
FIR, inventory/valuation list, invoices/receipts, CCTV footage (if any), and surveyor's report. Quick documentation speeds settlement.
Not always. Home policies have limits for business stock - a commercial burglary policy or add-on is recommended for significant business inventory.
No. Burglary policies exclude it; employee dishonesty needs a separate Fidelity Guarantee policy.