
Store Smart - Keep Stock Safe
Warehouses Icd Property Insurance Get Quote
Click to submit your details and receive a customised quote. Have questions about your coverage? Our team will call you within 1 business day.
Our Insurance Partners
Know your policy
Everything you need to know
What is Warehouses / ICD Property Insurance
Cover for warehouses, godowns and ICDs
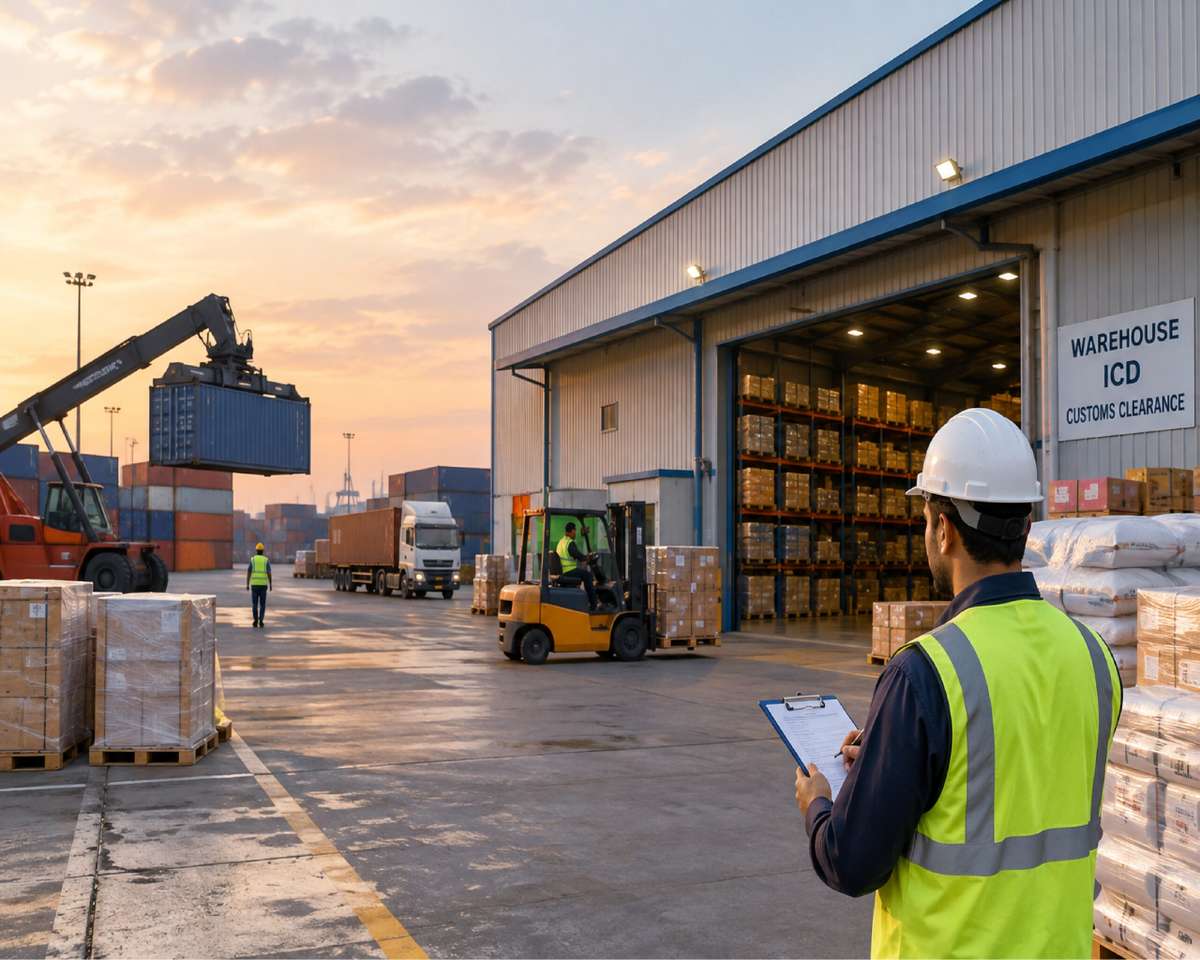
Warehouse/ICD property insurance protects goods, the warehouse structure, and on-site equipment against perils such as fire, theft, floods and accidental damage. ICDs (Inland Container Depots) are dry ports handling container storage and customs clearance – their insurance needs often combine property, stock and liability elements.
Why Is This Policy Vital?
Because stock sitting still is not risk-free
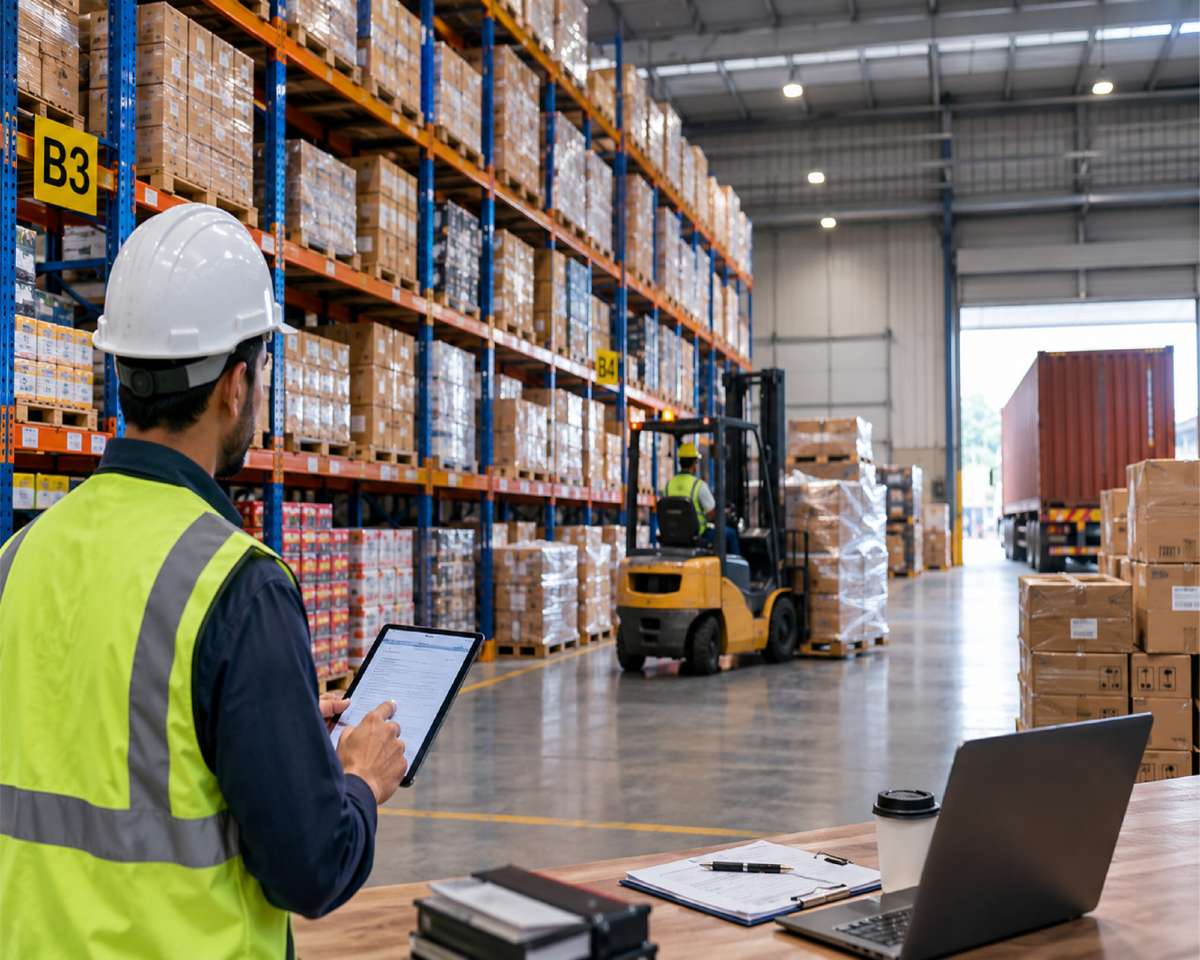
Warehouses hold months of working capital – a single incident can strain liquidity. (Think FMCG pallets or electronics worth crores.)
ICDs and multi-modal storage create multi-leg risk exposures; single-policy warehouse wording helps close coverage gaps.
Many buyers/suppliers require proof of warehouse cover in supply-chain contracts – it’s commercial hygiene.
Know your policy
Understand your insurance before buying
Who Needs This Insurance?
3PL & Logistics Providers
Cover your own warehouse and the client goods you hold in trust (needs "goods held in trust" wording).
FMCG / Retail Storage
Palletised goods and fast-moving inventories.
Importers / Exporters using ICDs
Container storage & customs-hold risk.
Manufacturers with storage yards
Raw materials and WIP protection.
Cold-chain / Agri Warehouses
Perishable stock needs tailored wording.
Types / Add-ons Commonly Offered
Stock on premises
Fixed sum insured, or a declaration / floater policy for fluctuating stock.
Transit cover
Goods moving in and out, under a marine cargo or inland transit policy.
Business Interruption
Loss of gross profit due to insured peril.
Burglary
Forcible-entry theft of stock and contents.
Racking & Equipment cover
Shelving, racking and forklifts used in the warehouse.
Cold-chain extension
Stock spoilage from refrigeration failure, where the extension is taken.
What This Policy Pays For
Fire & Explosion
Damage to stock and warehouse structure due to fire or explosion.
Flood & Water Damage
Loss from flood, inundation or storm water entering the warehouse. Gradual seepage and leakage are not covered.
Theft & Burglary
Loss due to forcible entry, theft, or burglary of stored goods.
Storm / Cyclone Damage
Damage caused by storms, cyclones, and high winds.
Damage to Racking & Shelving
Repair or replacement cost for damaged storage racks and shelving.
Goods in transit
Covered under a separate marine cargo or inland transit policy.
Business Interruption / Loss of Profit
Loss of gross profit due to insured peril halting operations.
Accidental damage (all-risks)
Available only under an all-risks or Industrial All Risks policy, not a standard fire policy.
Inclusions & Exclusions
✓Inclusions
- Fire, Lightning & Explosion — Direct physical loss to building and stock.
- Flood & Natural Perils — Flood, cyclone, earthquake per policy wording.
- Theft & Burglary — Forcible entry losses when declared.
- Warehouse-to-Warehouse / Transit (optional) — Continuous cover across legs.
- Racking & Plant — On-site equipment and storage infrastructure.
✗Exclusions
- Wear & Tear / Gradual Deterioration of stock or racking.
- Poor Packing or Inadequate Storage Practices (unless agreed).
- War, Nuclear & Sanctions-related Events.
- Delay, depreciation or loss of market — Not covered.
- Unreported / Undeclared Stock items.
FAQs
Warehouse covers storage on premises; warehouse-to-warehouse (marine wording) extends cover across transit legs between warehouses - useful for ICDs and multimodal moves.
Racking can be included in the property sum insured. Forklifts and other handling equipment are usually insured under a machinery breakdown or contractor's plant policy.
For fire cover, use a declaration policy (monthly stock declarations) or a floater across locations. First-loss sum insured is a burglary option.
BI (business interruption) covers insured gross profit reduction and continuing costs subject to indemnity period and policy wording. Confirm limits and waiting periods.
ICDs may need combined stock, plant and liability wording because they also handle customs and container storage - discuss specifics with underwriters.
Inventory lists, invoices, surveyor reports, photos, police FIR (if theft), and customs documents for ICD-stored cargo - complete docs speed settlement.