
Built For The Odd Ones - MISC Vehicle Cover That Actually Gets You
Misc Vehicle Insurance Get Quote
Click to submit your details and receive a customised quote. Have questions about your coverage? Our team will call you within 1 business day.
Our Insurance Partners
Know your policy
Everything you need to know
What is MISC Vehicle Insurance?
Compulsory PA for owner-driver (₹15 lakh) where the vehicle is owned by an individual. Optional PA for paid drivers, cleaners and passengers.
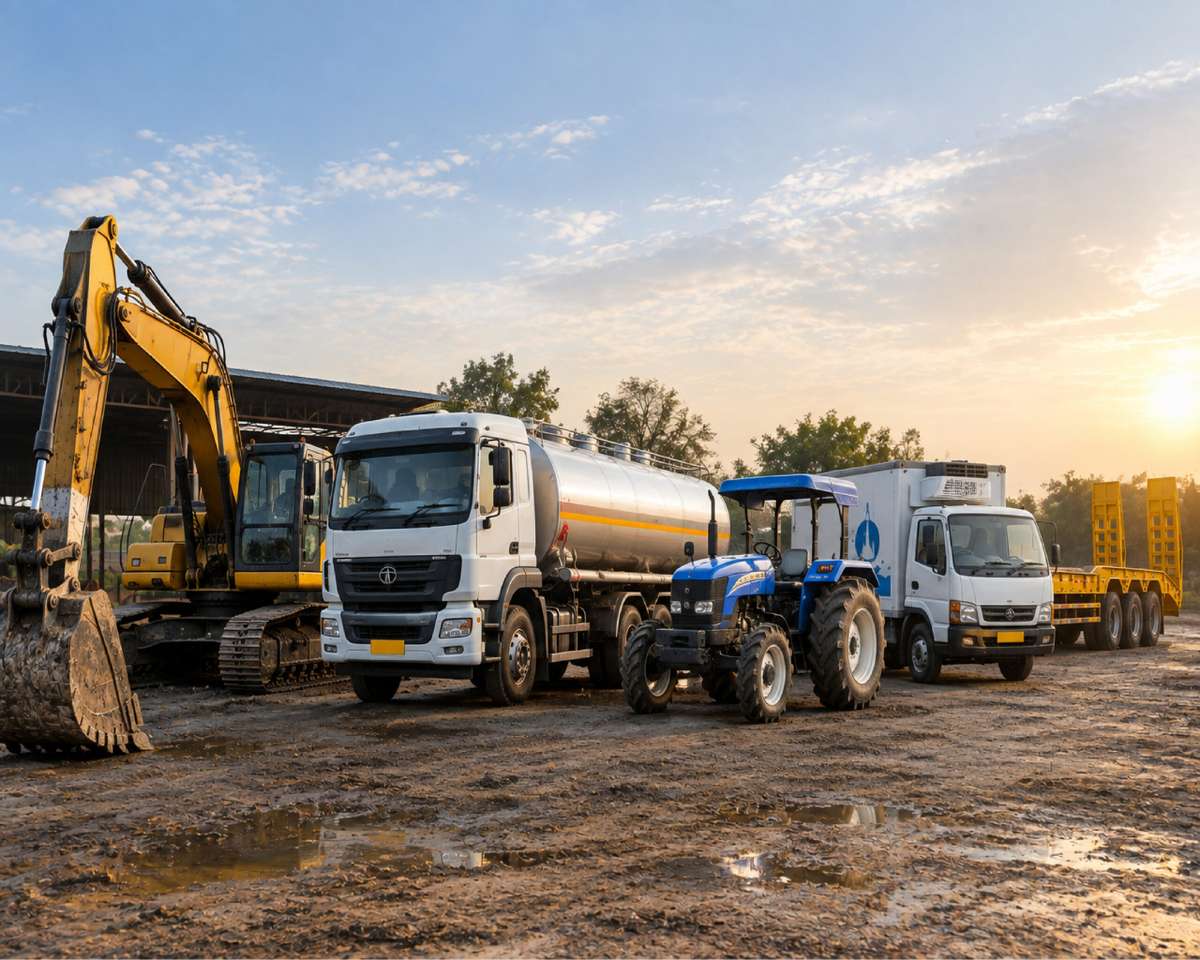
MISC Vehicle Insurance is a package policy for miscellaneous and special-type vehicles used commercially – think cranes, excavators, tractors, tankers, milk vans, trailers and other specialist machines. It typically insures Own Damage (OD) and Third-Party Liability, with IDV (Insured Declared Value) set per manufacturer list price and depreciation rules. This policy plugs gaps when a vehicle does not fit the regular commercial vehicle categories.
Why Is This Policy Vital?
Because Special vehicles need specialised cover.
Special vehicles cost money and downtime – one accident or theft can halt a jobsite or farm season.
Third-party liability for odd vehicles (cranes, tankers) can be huge – cover reduces legal and payout risk.
Package wording (OD + TP + add-ons) keeps contractors, farmers and fleet owners compliant and mobile.
Know your policy
Understand your insurance before buying
Who Needs MISC Vehicle Insurance?
Construction Contractors
Cranes, excavators, road rollers and mobile plant coverage.
Agricultural Operators
Tractors and harvesters.
Municipal / Utility Operators
Street sweepers, mobile cranes, ambulances and fire tenders.
Types / Add-ons Commonly Offered
Own Damage (OD) Cover
Repair or replace your vehicle after an accident.
Third-Party Liability
Your legal liability for death or injury to others (unlimited) and damage to their property (up to the statutory limit).
Passenger & PA Cover
Optional personal accident for drivers/operators.
Breakdown / Roadside Assistance
On-site help and towing (optional).
Theft, Fire & Natural Perils
OD plus calamity protection.
Special Attachments Cover
Indemnity for mounted plant/accessories (booms, buckets).
What MISC Vehicle Insurance Pays For
Collision Damage
Accidental impact repairs.
Fire & Explosion
Vehicle fire & allied perils.
Theft & Malicious Damage
Theft or vandalism.
Third-Party Liability
Property damage and bodily injury to others.
Natural Disasters
Flood, cyclone, earthquake damage to vehicle.
Strikes & Riots
Political or civil disturbance damage.
Accessories & Attachments
Insured mounted equipment replacement.
Passenger / Operator PA
Personal accident benefits for driver/operator.
Inclusions & Exclusions
✓Inclusions
- Own Damage — Repair or total-loss settlement for the insured vehicle per IDV.
- Third-party Liability — Statutory cover for third-party death/injury and property damage.
- Fire & Theft — Loss due to fire, explosion, theft or attempted theft.
- Natural Calamities — Flood, cyclone, earthquake losses (where policy includes).
- Accessories & Fitted Equipment — Cover for attachments if declared.
✗Exclusions
- Wear & Tear / Mechanical Breakdown — From gradual deterioration (unless engineering cover bought separately).
- Driving under the influence, without a valid licence, or by an unauthorised driver — Own-damage claims are rejected. Third-party claims are paid by the insurer, which may then recover the amount from the owner.
- Contractual Liabilities not covered unless agreed.
- Punitive fines, penalties or indirect/consequential losses.
FAQs
Vehicles not covered by standard passenger/goods categories - cranes, farm tractors, mobile plants and special trailers. Check the vehicle's classification and policy wording.
Yes, third-party liability is compulsory under the Motor Vehicles Act for all motor vehicles in India. OD cover is optional but recommended for commercial vehicles.
IDV is typically the manufacturer's listed selling price adjusted for age-based depreciation per insurer schedule; accessories may need separate declaration. For vehicles over five years old, IDV is agreed between you and the insurer.
Yes - declare them and take special attachments cover or include in package wording. Un-declared accessories may be excluded at claim.
FIR (if theft/criminal act), driver's license, RC book, policy copy, repair bills/estimate and photos; insurer surveyor will inspect.
They can be, if declared and covered under policy extensions; otherwise unauthorized driver exclusions may apply.