
Ship It Safe - Marine Insurance That Keeps Cargo Moving
Marine Insurance Get Quote
Click to submit your details and receive a customised quote. Have questions about your coverage? Our team will call you within 1 business day.
Our Insurance Partners
Know your policy
Everything you need to know
What is Marine Insurance
Cargo Covered, From Warehouse to Warehouse
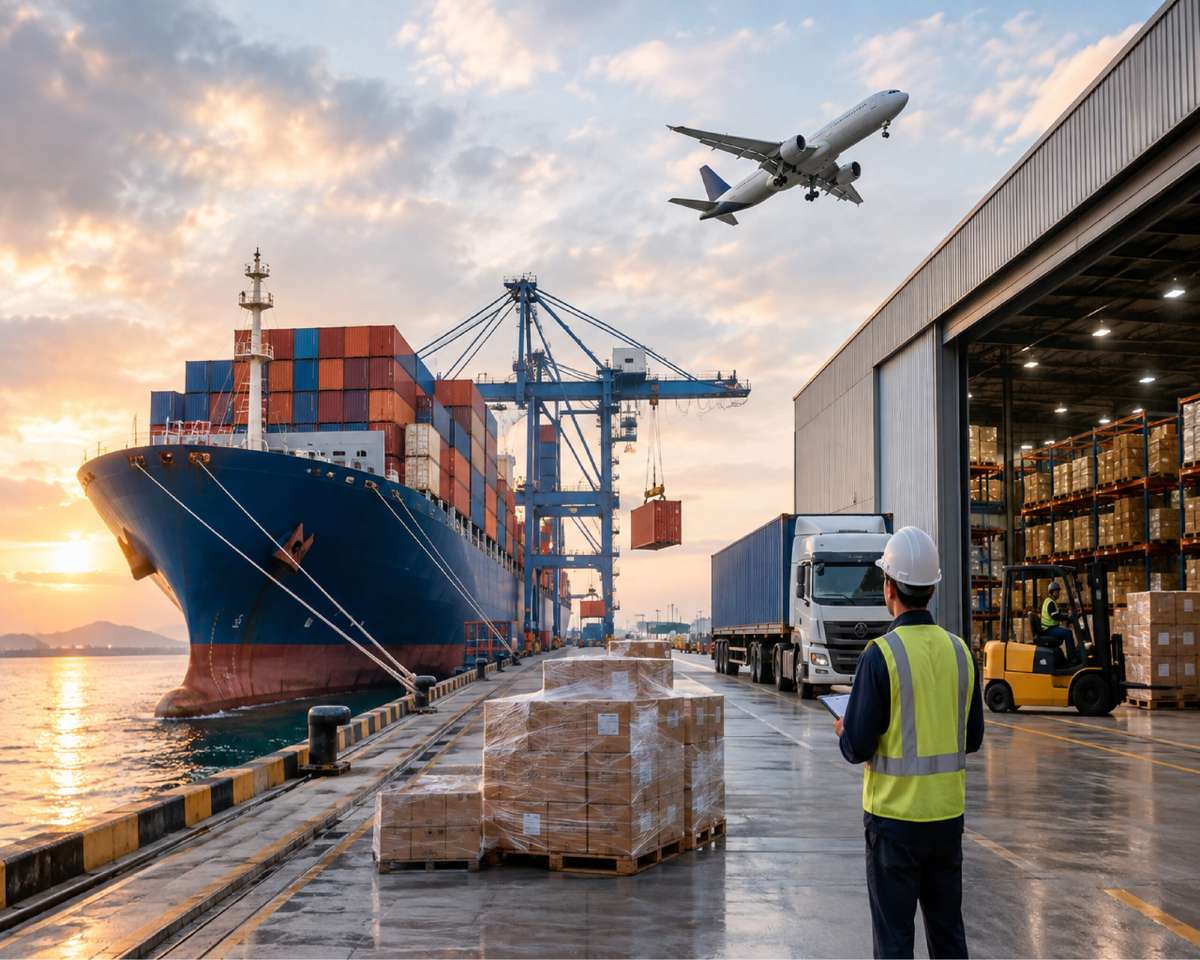
Marine insurance protects goods and shipping interests against physical loss or damage during carriage by sea, air or land. Policies can be quoted as cargo, hull & machinery, or liability (P&I). Cargo cover commonly uses Institute Cargo Clauses (ICC) A/B/C – ICC A being the broadest (‘all risks’) option and ICC C the most limited. You can buy warehouse-to-warehouse wording to keep cover continuous across multiple legs.
Why Is This Policy Vital for Business Owners?
Trade Moves Fast – So Should Your Cover
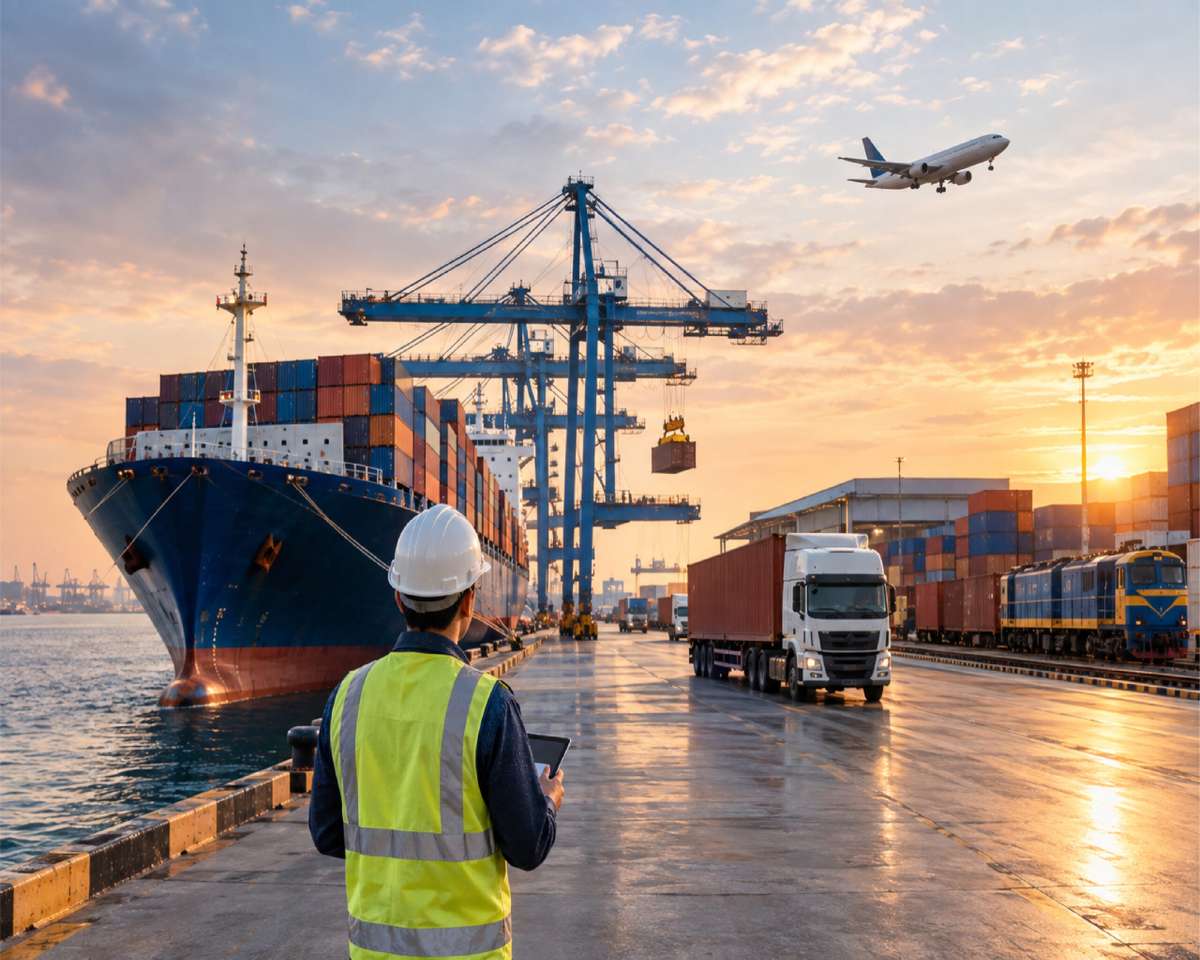
India is a major trading nation; damage or loss can halt supply chains and squeeze working capital.
Exporters/importers need reliable cover to satisfy LCs and commercial terms (CIF, CFR, etc.).
Inland container depots (ICDs), ports and multimodal moves bring local complexities – marine insurance stitches the gaps.
Know your policy
Understand your insurance before buying
Who Needs Marine Insurance?
Importers & Exporters
Protect shipments and meet contract terms.
Freight Forwarders & Logistics Providers
Liability and cargo handling risks.
Manufacturers with Global Supply Chains
Inbound raw material and outbound finished goods cover.
Warehouse / ICD Operators
Cargo in transit through your facility. For goods in storage, see Warehouse & ICD Property Insurance.
Shipping Companies & Charterers
Hull, machinery and P&I liability exposures.
Types / Add-ons Commonly Offered
Marine Cargo Insurance
ICC A / B / C options.
Inland Transit / Transit Insurance
Road/Rail within India.
Warehouse-to-warehouse
Continuous cover from the origin warehouse to the destination warehouse, including the inland legs.
Hull & Machinery
Physical damage to the vessel.
P&I
Shipowner's third-party liabilities, usually through a P&I club.
Freight & Interest Insurance
Cover freight loss / shipper's interest.
What Marine Insurance Covers
Ocean Perils (sinking, grounding)
Loss or damage to cargo due to vessel sinking, grounding, or capsizing at sea.
Fire on Board
Damage to cargo caused by fire or explosion aboard the carrying vessel.
Theft, Pilferage & Non-delivery
Covered under ICC (A) or with a TPND extension.
Loading / Unloading Damage
Full cover under ICC (A); ICC (B) and (C) cover only limited cases.
Weather / Cargo Damage
Damage to cargo caused by adverse weather conditions during the voyage.
Collision / Contact
Loss or damage arising from the vessel's collision or contact with another object.
Inland Transit Damage
Damage to cargo during road or rail transit within India before or after the sea voyage.
Warehouse-to-Warehouse clause coverage
Continuous coverage for cargo from the origin warehouse to the final destination warehouse.
Inclusions & Exclusions
✓Inclusions
- Perils as per chosen clause (ICC A/B/C) — e.g., loss/damage from collision, grounding, fire (depending on clause).
- Loading, unloading and handling damage (if covered by clause).
- General average and salvage charges — covered under ICC A, B and C.
- Theft / pilferage — under ICC A or a TPND extension.
- Warehouse-to-warehouse and multimodal transit (if specified).
✗Exclusions
- Poor packing / improper stowage (unless insurer has agreed).
- War and nuclear risks (unless separately covered).
- Delay, depreciation or consequential loss (unless expressly insured).
- Sanctions or prohibited-country consignments (subject to regulatory rules).
- Inherent vice, ordinary leakage, loss in weight or volume, and ordinary wear and tear.
FAQs
ICC A is the broadest (near all-risks). ICC (B) covers the ICC (C) perils plus earthquake or lightning, washing overboard, entry of sea or river water, and total loss of a package during loading or unloading. ICC C is the most restricted. Higher cover = higher premium.
Depends on Incoterms. Under CIF and CIP the seller arranges cover; under FOB, CFR and EXW the buyer usually does. Check your contract and LC instructions.
Only during the ordinary course of transit, and only if theft is covered (ICC A or a TPND extension). Cover ends after a set period once goods reach the final warehouse or stay in storage outside normal transit. Longer storage needs a separate property or storage policy.
Simple cargo claims with clear documentation can be closed in weeks; complex losses involving salvage or surveyor investigations can take months.
Generally no. Policies carry a sanctions clause, and insurers cannot pay claims that would breach applicable sanctions.
Bill of lading/airway bill, packing list, commercial invoice, surveyor report, and any customs/port documents.