
Double Your Health Coverage, Add higher cover above your existing policy for a lower premium than a bigger base plan.
Super Top Up Health Insurance Get Quote
Click to submit your details and receive a customised quote. Have questions about your coverage? Our team will call you within 1 business day.
Our Insurance Partners
Know your policy
Everything you need to know
What is Super Top Up Health Insurance
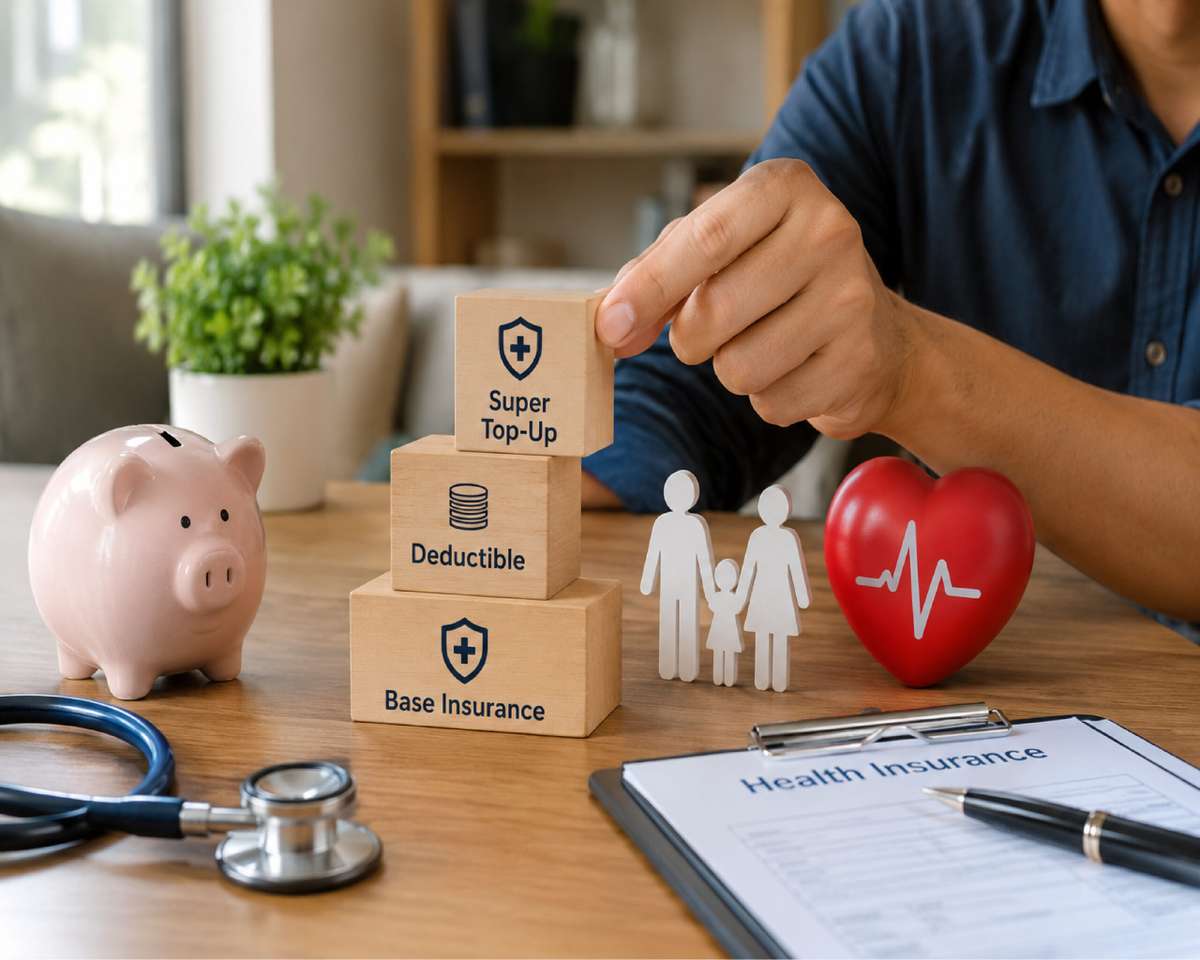
A super top-up pays hospital bills once your total claims in a year cross a deductible you choose. It works alongside your own or your employer's health policy.
You pay the deductible you choose (for example ₹5 lakh) from your base policy or your pocket.
Why Is This Policy Vital for Smart Planners
Why a super top-up matters
A super top-up usually costs much less than raising your base sum insured by the same amount. We'll compare both for your family.
Know your policy
Understand your insurance before buying
Who Needs Super Top Up Health Insurance?
Corporate Employees
Group insurance typically covers ₹3-5 lakh; super top-up adds ₹15-25 lakh at ₹6,000-10,000 annual premium.
Existing Policyholders
Base policy insufficient for rising medical costs; top-up extends coverage without buying expensive new policy.
High Medical Risk Families
Diabetics, heart patients, and chronic disease families needing extra cushion beyond base coverage limits.
Senior Citizens
Elderly parents' base policies exhausted; super top-up provides affordable additional coverage despite age.
Multi-Hospitalization Families
Multiple family claims depleting base policy; super top-up covers subsequent hospitalizations same year.
Budget-Conscious Planners
Want ₹50 lakh total coverage but can't afford ₹50 lakh base premium; combine ₹5L base + ₹45L top-up smartly!
Types / Add-ons Commonly Offered
Individual Super Top-Up
Personal deductible-based coverage.
Family Floater Top-Up
Shared family coverage after deductible.
Aggregate Deductible
Deductible applies to total annual claims.
Top-up vs super top-up
A top-up applies the deductible to each claim; a super top-up applies it to your total claims in the year.
Critical Illness Add-On
Additional lump-sum for specified diseases.
Critical Illness (optional)
Lump-sum payout on diagnosis, where the insurer offers it.
What Super Top Up Health Insurance Covers
Post-Deductible Hospitalization
Hospital expenses that exceed your chosen deductible limit.
ICU Charges
Intensive care unit costs beyond the deductible.
Surgery Expenses
Surgeon fees, operation theatre charges, and related costs above the deductible.
Pre-Post Hospitalization
Medical expenses incurred before admission and after discharge.
Daycare Procedures
Treatments requiring less than 24 hours of hospitalization.
Ambulance Charges
Emergency ambulance transport costs to the hospital.
Organ Donor Expenses
Medical costs of the donor for organ transplant surgery.
Room rent
As per the super top-up policy's own room rent terms, once the deductible is crossed.
Multiple Hospitalizations
Cumulative claims across several hospitalizations in the same policy year.
Annual Health Check-up
Preventive health check-ups covered once a year.
COVID-19 Treatment
Hospitalization and treatment costs for COVID-19.
Inclusions & Exclusions
✓Inclusions
- Post-Deductible Coverage — All medical expenses exceeding the deductible you choose are covered up to the super top-up sum insured.
- Multiple Claims Coverage — Aggregate deductible counts all claims together; kicks in when annual claims exceed deductible.
- Standard health benefits — Pre- and post-hospitalisation, day care and ambulance, as per the super top-up's own wording, once the deductible is crossed.
- Room rent — As per the super top-up policy's own room rent terms, once the deductible is crossed.
✗Exclusions
- Below Deductible Claims — Expenses below the deductible you choose are not covered by the super top-up.
- Pre-existing Diseases — Waiting period of up to 3 years applies unless specifically waived.
- Cosmetic Procedures — Aesthetic surgeries and beauty treatments excluded like base policies.
- First 30 Days — Initial waiting period for illnesses (except accidents) similar to regular health insurance.
- Maternity (Usually) — Most super top-ups exclude maternity; some offer after 3-4 year waiting periods.
FAQs
A top-up applies the deductible to each claim; a super top-up applies it to your total claims in the year. A super top-up is usually better if you may have more than one hospitalisation.
Yes. But you'll pay the deductible from your pocket. It is better to combine a base policy with a super top-up for complete coverage.
With a ₹5 lakh deductible: a ₹2 lakh claim and then a ₹4 lakh claim in the same year total ₹6 lakh, so the super top-up pays ₹1 lakh.
A super top-up usually costs much less than raising your base sum insured by the same amount. We'll compare both for your family.
Yes. Many people use their corporate or base policy to cover the deductible, and the super top-up for the amount above it.
Yes, after a waiting period of up to 3 years. Portability from your base policy can reduce the wait.